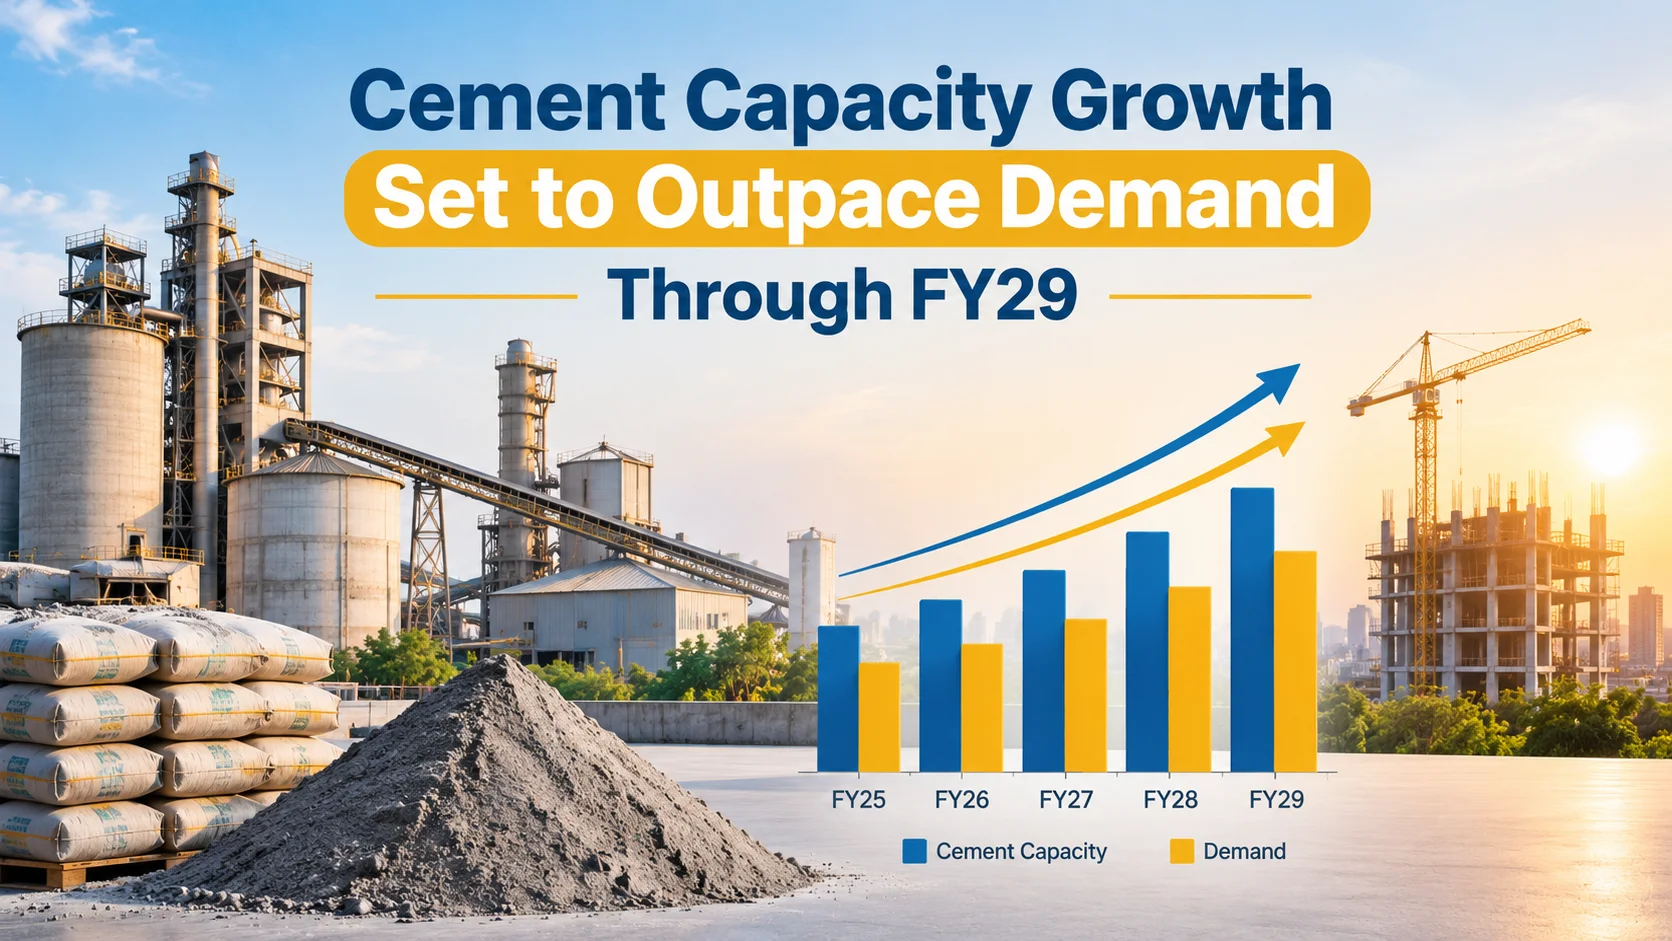
The cement industry is expected to face a prolonged period of excess capacity, with supply likely to grow faster than demand over the next few years. Installed cement capacity is projected to increase from around 654 million tonnes (mt) in FY25 to 702 mt in FY26, before reaching approximately 867 mt by FY29. Cement demand is also expected to remain healthy but is projected to grow at a slower pace than capacity. As a result, industry capacity utilisation could remain below 70% through FY29, according to industry estimates. Cement manufacturers are expected to add around 42 mt of capacity in FY27, 67 mt in FY28 and another 56 mt in FY29. Meanwhile, cement consumption is forecast to increase from approximately 486 mt in FY26 to 596 mt by FY29. Demand growth is estimated at 8.7% in FY26 and is expected to moderate to around 7.1% annually between FY27 and FY29. The continued addition of new production capacity could keep the supply-demand balance under pressure. With capacity expanding faster than consumption, cement manufacturers may face limited pricing power over the coming years. The trend could also have implications for the construction and real estate sectors, particularly through changes in cement prices, construction costs and project margins.
Cement Capacity Growth Set to Outpace Demand Through FY29
Oct 01 2026
Latest Newsletter
Chennai Property Tax Deadline Today: September 30 Last Day to Pay Without Penalty
Sep 30 2026
Interest Rates May Rise to 5.50 percentage in October as Inflation Broadens
Sep 29 2026
Housing Sales Decline 6 percentage in Top 9 Cities Amid Weakening Demand
Sep 28 2026
Directs Commercial Sites to Be Assessed Under Existing Master Plan Rules
Sep 26 2026
TN Housing Board to Build New Homes Based on Public Demand
Sep 25 2026